Global Payments Weekly 2026W35


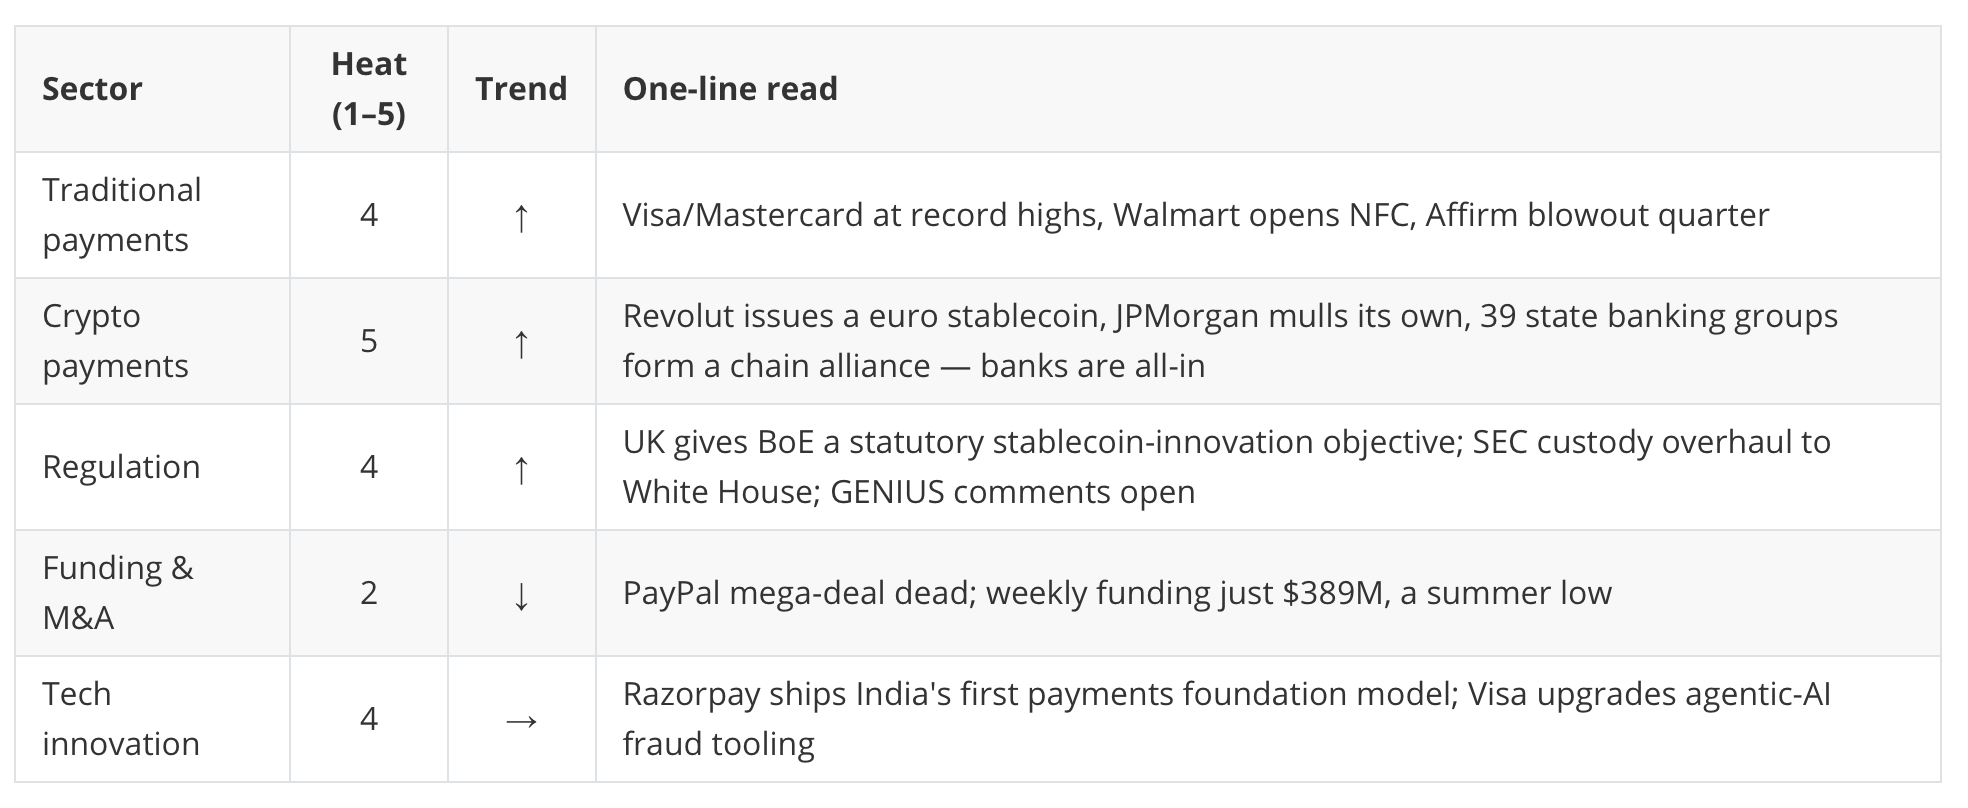
- 核心观点:本周传统支付与加密支付行业的关键动态聚焦于大型支付公司的资产定价纪律、零售巨头NFC支付开放带来的市场格局重估,以及稳定币在监管与商业银行推动下加速进入合规化与代币化美元的多路径竞争阶段。
- 关键要素:
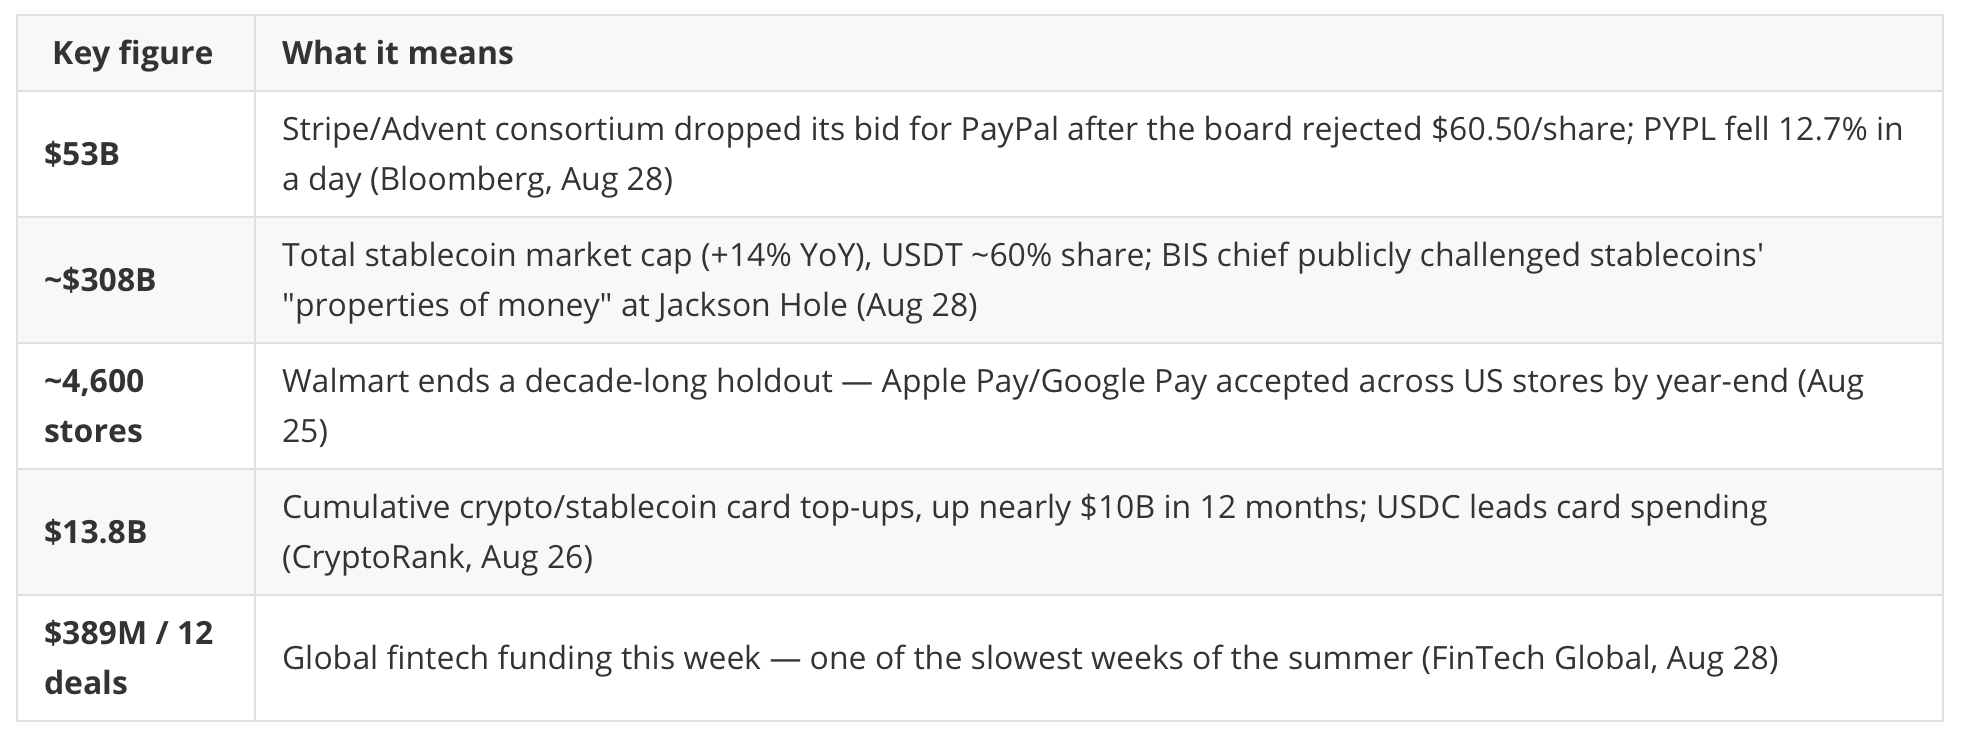
- PayPal收购案因每股60.50美元被拒而告吹,财团放弃而非提价,显示买方对支付类资产的定价纪律强于预期,PYPL股价回吐约30%涨幅,大型并购叙事或暂时降温。
- 沃尔玛开放NFC受理,同时推进自有OnePay和BNPL业务,对发卡行和网络而言是实体卡接触式非接支付量的结构性利好,需关注其结账环节的竞争反应。
- Revolut在MiCA生效下下架USDT并发行合规欧元稳定币EURR,且发行方为Stripe的Bridge,支付巨头正成为稳定币“合约制造商”,凸显MiCA的驱逐与培育双重效应。
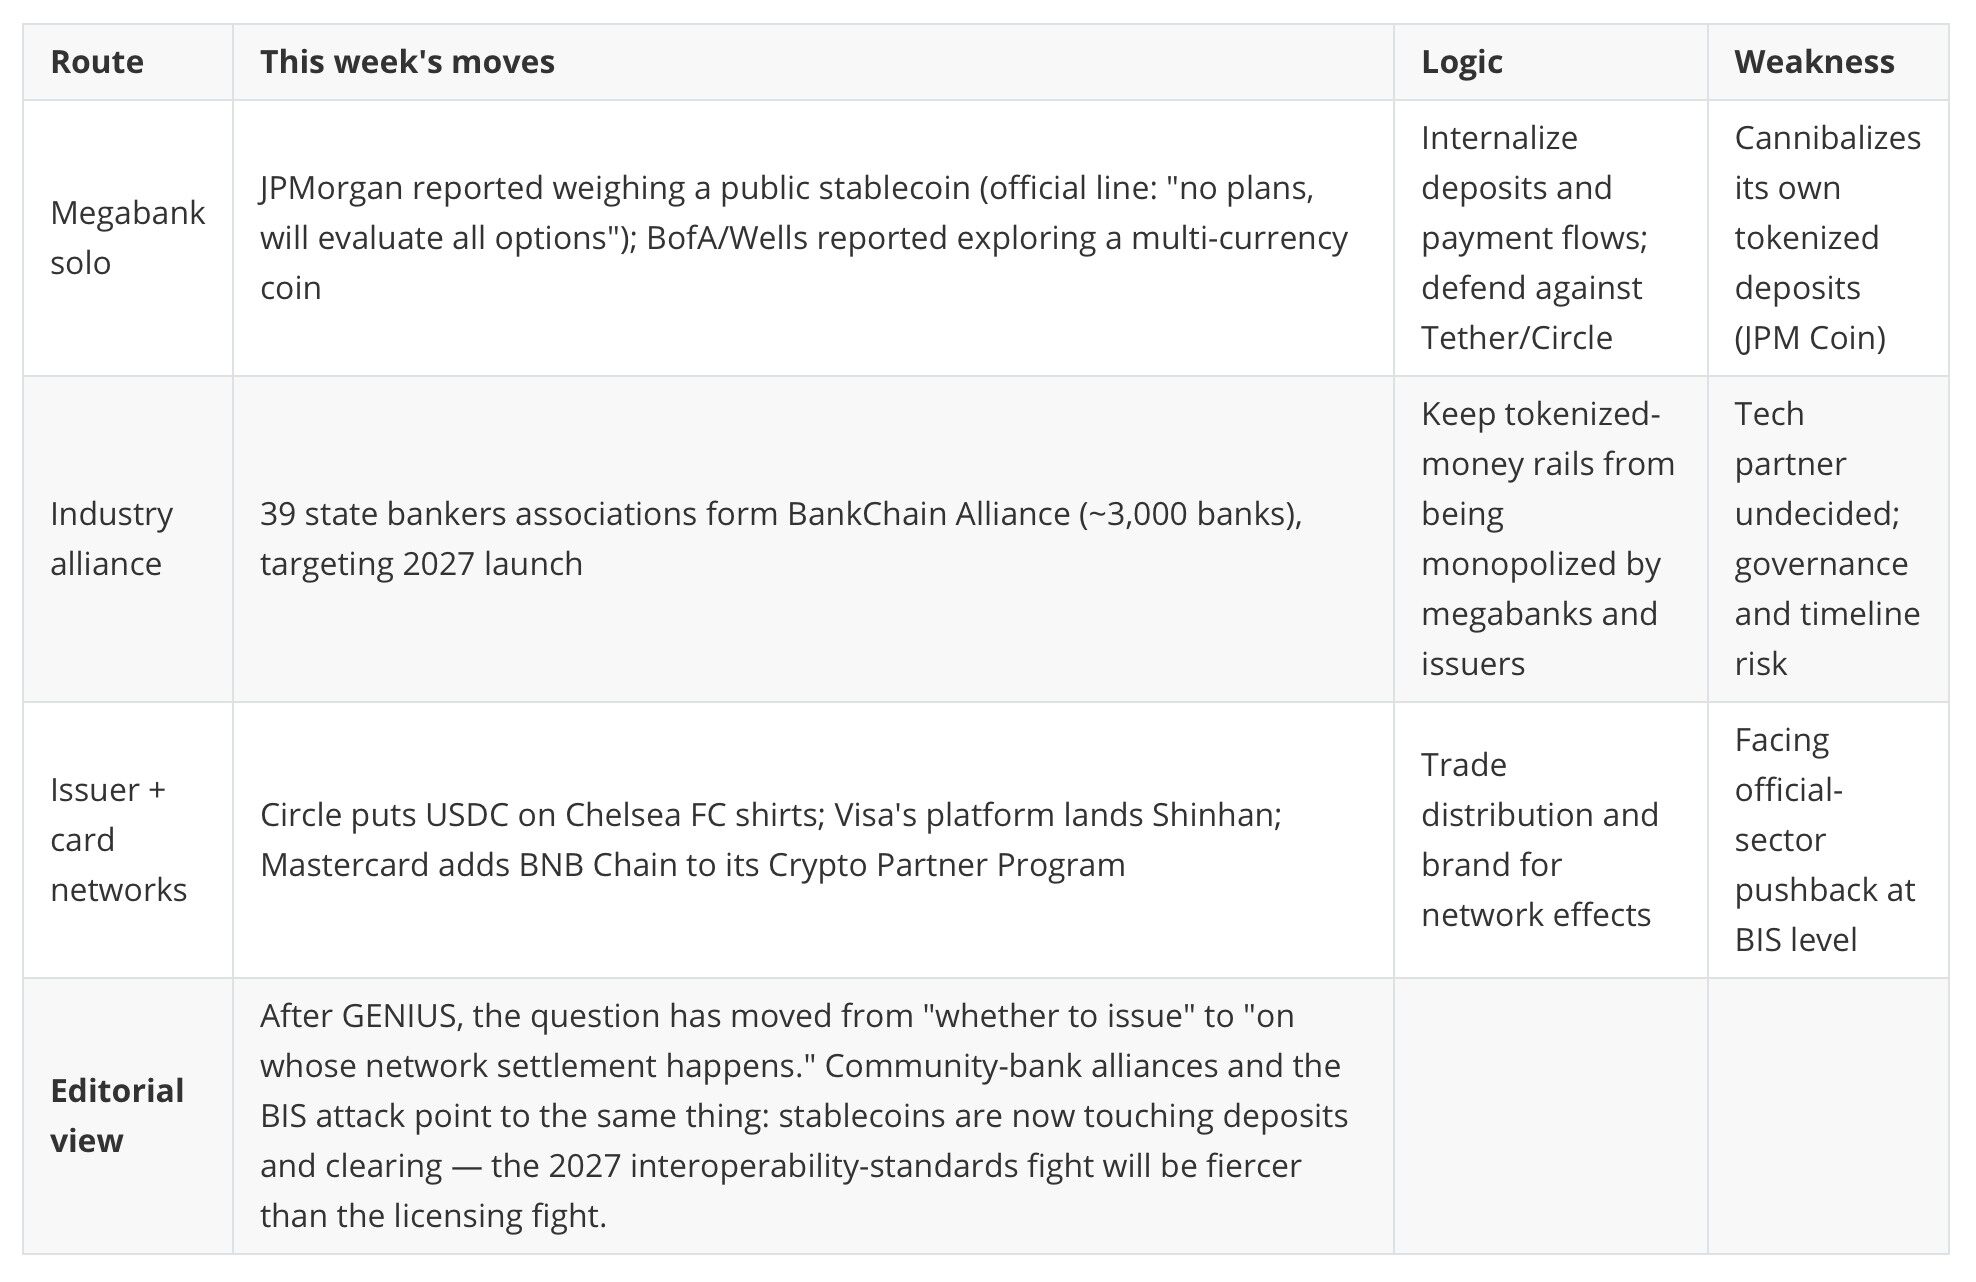
- 摩根大通(独自)、社区银行联盟及TCH(独立路线)并行推进代币化美元,至少三条路径并存,互操作性而非发行成为基础设施提供商的下一个竞争焦点。
- Swift推迟ISO 20022迁移,而TCH RTP宣布2027年上半年跨境试点且链上结算成熟,传统报文迁移的拖延为替代方案扩大时间窗口。
Author / Editor: WANG TAI
Coverage period: Aug 24 – Aug 30, 2026 (Week 35) · For traditional & crypto payments practitioners · ~4-min read
1. The Week at a Glance
2. Industry Thermometer
3. Key Events of the Week

Why these matter (editorial analysis)
- PayPal deal collapse: the consortium walked rather than raised after a $60.50/share rejection — buy-side price discipline on payments assets is stronger than the market assumed. PYPL gave back the ~30% gained since talks surfaced; expect the large-cap consolidation narrative to cool near-term.
- Walmart opens NFC: this is repositioning, not surrender — Walmart is simultaneously pushing its own OnePay and BNPL. For issuers and networks it is a genuine card-present contactless volume windfall; watch how aggressively OnePay counters at checkout.
- Revolut EURR: MiCA's expulsion effect (USDT delisting) and incubation effect (a compliant euro stablecoin) landed at the same company in the same week — and the issuer is Stripe's Bridge. Payment giants are becoming the stablecoin "contract manufacturers."
- JPMorgan & BankChain: megabanks solo, community banks in alliance, TCH on its own track — at least three parallel routes to tokenized dollars. For infrastructure providers, interoperability, not issuance, becomes the next competitive interface.
- Swift's ISO 20022 delay: with TCH's RTP announcing a cross-border pilot for H1 2027 and on-chain settlement maturing, every slip in legacy messaging migration hands the alternatives a wider time window.
4. Crypto / Web3 Deep Dive
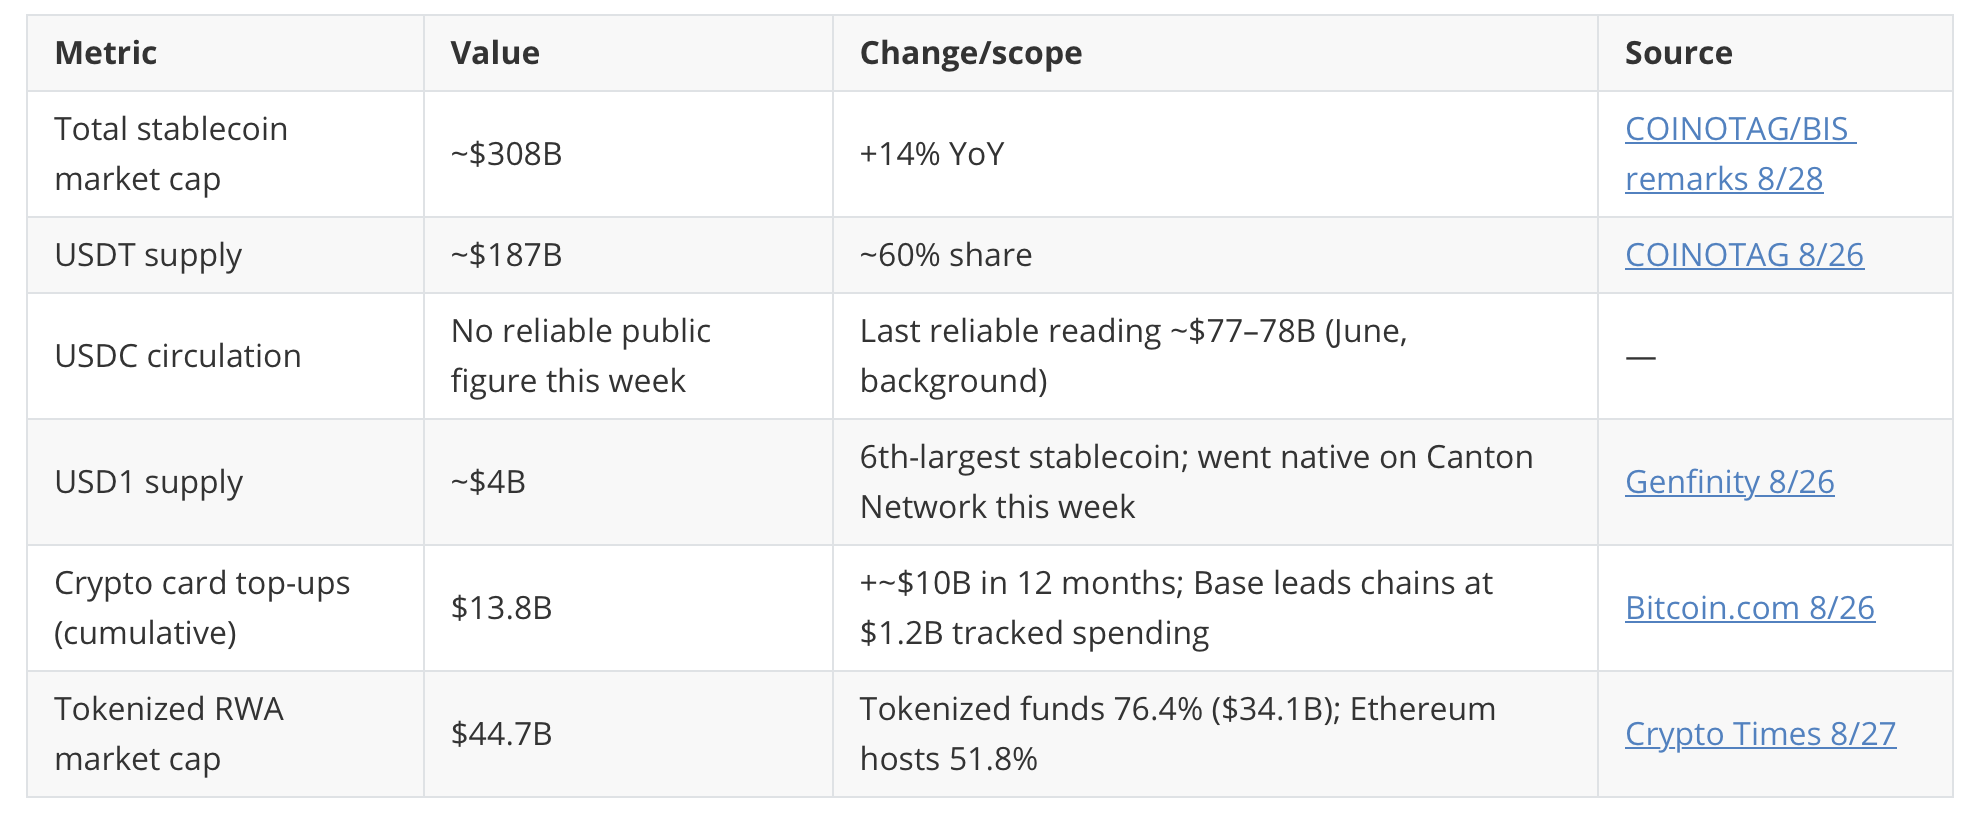
4.1 Stablecoin data dashboard
4.2 Theme of the week: banks pile in — three parallel routes to tokenized dollars
4.3 Voices of the week

4.4 Regulatory week in brief
US: SEC sent its crypto-custody rule overhaul for advisers/funds to the White House (OIRA) (The Block 8/26); the Blockchain Association backed Treasury's GENIUS Section 3 proposed rules — comments due Oct 19 (The Block 8/25). UK: BoE gets a statutory stablecoin-innovation objective (see Key Events). EU: MiCA enforcement effects turn visible — Revolut delists USDT and issues compliant EURR. No major new policy from Mainland China or Hong Kong this week (background: PBOC expanded e-CNY operators to 30 banks mid-August; Hong Kong's HKDAP advancing in institutional use).
5. Traditional vs. Crypto Payments

6. Regional Watch

7. Action Items for Practitioners
For traditional payments practitioners
- Re-price your wallet channel strategy: Walmart's NFC opening delivers structural card-present contactless volume in the US — issuers and acquirers should model the tap-to-pay share shift now, and watch OnePay's counter-moves at checkout.
- Don't slow ISO 20022: Swift's deferral is a buffer, not an exemption — keep structured-address work on schedule, and add TCH RTP's cross-border pilot (H1 2027) to your cross-border product roadmap review.
- Pick BNPL partners on credit quality: the Affirm/Klarna divergence shows underwriting, not GMV growth, determines partner durability — build performance triggers into co-brand and distribution deals.
For crypto payments practitioners
- Align EEA products with MiCA now: Revolut's USDT delisting is the signal — plan compliant-stablecoin substitution (EURC/EURR-class) and liquidity migration for European flows within the year.
- File GENIUS comments (due Oct 19): the foreign-issuer prohibition bites July 2028 — lock in your structural path (US entity, agency issuance, or exit) during the comment window.
- Position at the bank-interoperability layer: with megabanks, state-bank alliances and card networks building in parallel, the "connector" role (compliant settlement, cross-network clearing) is scarcer than issuance — the Shinhan × Visa template is replicable with regional banks.
8. Watchlist for Next Week
- Aug 31: Revolut's USDT delisting across the EEA — watch where European USDT liquidity migrates (EURC/EURR/USDC) and whether other platforms follow.
- Sept 1: Wero launches in Luxembourg; TCH RTP's new rules take effect in September — two bellwethers for legacy rails' self-renewal in Europe and the US.
- The announcement window ahead of Money20/20 Middle East (Sept 14–16, Riyadh) — expect concentrated Saudi/UAE licensing and product news; also track large banks' and issuers' position papers in the GENIUS comment docket (closes Oct 19).
All data and events are drawn from public reporting; links point to original sources. Editorial analysis reflects judgment based on public information and is not investment advice.